

Selling Your HDB Flat Soon? Here's How Much Cash You'll Actually Get After CPF Refunds
Thinking of selling your HDB flat in Singapore? Before putting your property on the market, there's one important question you should ask: How much cash will I actually receive after selling my flat?
Many HDB homeowners focus on their property's potential selling price. After all, seeing neighbouring flats sell for $600,000, $700,000 or even more can be exciting.
But there is a significant difference between your HDB resale price and the actual cash proceeds you receive.
Your outstanding housing loan, CPF refunds, accrued interest and selling expenses can affect how much money you walk away with.
Whether you're planning to upgrade to a condominium, purchase a larger HDB flat, downsize for retirement or simply explore your options, understanding your estimated sale proceeds is an essential first step.
In this guide, we'll explain how HDB selling proceeds work in 2026, the costs you should consider and how to estimate your cash before selling.
1. How Much Is Your HDB Flat Worth in 2026?
Before calculating your selling proceeds, you need a realistic estimate of your property's market value.
HDB resale prices can vary significantly, even among flats within the same estate.
Some of the factors affecting your property's selling price include:
Location: Proximity to MRT stations, shopping malls, schools and amenities.
Flat type: Whether your property is a 3-room, 4-room, 5-room, executive flat or maisonette.
Remaining lease: Buyers may consider how the remaining lease affects their financing and future plans.
Floor level: Higher-floor units can command a premium in certain locations.
Condition and renovation: Well-maintained properties may appeal to buyers seeking move-in-ready homes.
Recent transactions: Comparable flats sold nearby help establish a realistic price range.
For example, two 4-room HDB flats in the same town may attract different offers because one is near an MRT station while the other is farther away.
Even the direction a unit faces, its layout and the surrounding environment can influence buyer preferences.
Before listing your HDB flat, study comparable completed resale transactions rather than relying only on advertised asking prices.
A professional assessment can also help you understand where your property stands in the current market.
2. How Much Cash Will You Get After Selling Your HDB?
Your HDB selling price is not the same as your net cash proceeds.
When you sell your flat, the sale proceeds are generally used to settle your outstanding housing loan, required CPF refunds and applicable selling expenses.
Here's a simplified example.
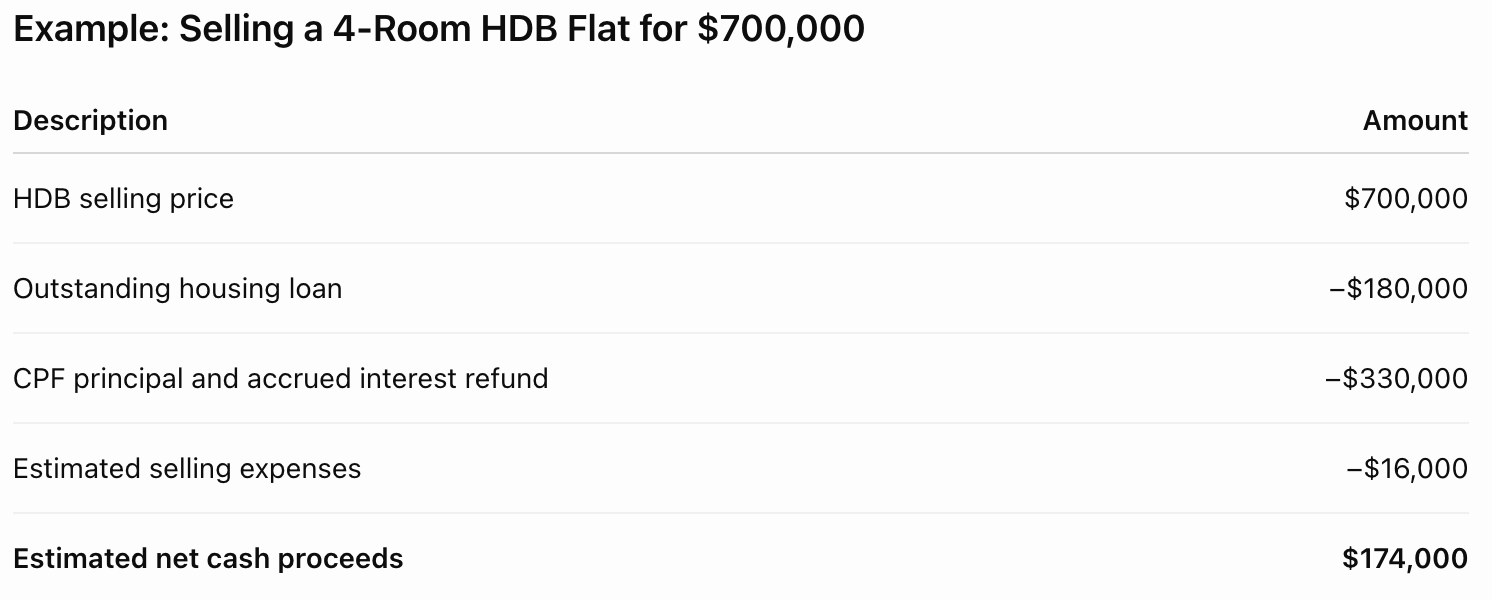
Illustrative example only. Actual proceeds depend on your financial circumstances, CPF requirements and transaction costs.
In this example, the homeowner sells the HDB flat for $700,000 but receives approximately $174,000 in net cash after the listed deductions.
The $330,000 CPF refund is returned to the owner's CPF account, rather than disappearing as an expense.
Depending on CPF rules and the owner's circumstances, those funds may be available for another eligible housing purchase.
This is why calculating your expected cash proceeds before selling is so important.
A homeowner who assumes that the entire selling price is available for the next purchase may encounter unexpected financing problems.
3. What Happens to Your CPF When You Sell Your HDB?
This is one of the most important financial considerations for HDB sellers.
If you used CPF savings to purchase your HDB flat, pay your housing loan or cover eligible housing expenses, you will generally need to refund the CPF amount withdrawn together with the accrued interest when you sell.
What is CPF accrued interest?
Accrued interest is the interest your CPF savings would have earned if the money had remained in your CPF account.
For example, suppose you used $200,000 from CPF towards your HDB purchase and mortgage payments.
Over the years, the amount you need to refund may increase because of accrued interest.
The actual amount depends on when and how much CPF was withdrawn and the applicable interest calculations.
Does CPF accrued interest mean you lose money?
Not exactly. The CPF refund is returned to your CPF savings for your benefit.
However, it reduces the amount of your property sale proceeds that you receive directly as cash and you lose out on opportunity costs.
For homeowners planning to purchase another property, the distinction between available cash and CPF savings is important.
What if you're above 55 years old?
CPF housing refunds for homeowners aged 55 and above may first be used to meet the required retirement sum in their Retirement Account.
Consequently, not all refunded CPF savings will necessarily be available for your next property purchase or immediate withdrawal.
Homeowners approaching retirement should review their CPF position carefully before deciding to sell.
4. What Costs Should You Consider When Selling Your HDB Flat?
Apart from CPF refunds and the outstanding mortgage, there are other potential expenses.
Property agent commission
If you engage a property agent to market and sell your HDB flat, you will need to account for the agreed agency commission and applicable GST.
Commission rates are negotiable rather than government-fixed.
Your agent should explain the scope of services, commission arrangements and expected selling process before you engage them.
Legal and administrative fees
Selling your HDB flat involves conveyancing, documentation and administrative procedures.
The applicable charges depend on factors such as whether HDB or a private solicitor handles your conveyancing.
Other outstanding charges
Depending on your circumstances, you may also need to account for outstanding property-related payments, upgrading costs or an applicable resale levy.
Seller's Stamp Duty
Most owners selling an ordinary HDB flat after fulfilling their five-year Minimum Occupation Period would generally be outside the usual Seller's Stamp Duty holding period. However, stamp duty liability depends on the relevant purchase date and circumstances. Sellers should check the applicable rules instead of assuming that no duty is payable.
The important point: Your actual net selling proceeds should be calculated after reviewing all applicable obligations and expenses.
5. Should You Sell Your HDB Flat Soon or Wait?
There is no single answer that applies to every homeowner.
The right time to sell depends on your property's market value, your financial situation and what you intend to do after selling.
Consider these three scenarios.
Scenario A: You're planning to upgrade to a condominium
If you have fulfilled your HDB's applicable Minimum Occupation Period and are considering a private property upgrade, you should first determine:
Your estimated HDB selling price
Your available cash and CPF proceeds
Your outstanding mortgage
The down payment required for your next property
Applicable stamp duties and other purchase expenses
Whether your income can comfortably support the new housing loan
Selling at a higher price does not necessarily mean that upgrading is financially advantageous if your replacement property has also increased substantially in price.
The objective should be to understand your overall financial position after both transactions.
Scenario B: You're planning to upgrade to a larger HDB flat
Perhaps you currently own a 3-room or 4-room HDB flat and need more space for your growing family.
Before selling, compare the expected selling price of your existing home against the cost of a suitable replacement flat.
You should also consider the transaction timelines, financing requirements and whether temporary accommodation could become necessary.
A properly planned sale-and-purchase timeline can help reduce unnecessary financial and logistical pressure.
Scenario C: You're considering downsizing for retirement
If your children have moved out, selling a larger HDB flat and purchasing a smaller property may help release some housing equity. However, the actual benefit depends on the cash proceeds, CPF refund requirements, cost of the replacement property and your retirement needs. For owners aged 55 and above, CPF retirement requirements are particularly important. Downsizing can be worth exploring, but homeowners should make their decision based on the complete financial picture.
6. Should You Renovate Your HDB Before Selling?
Many sellers assume that renovating their flat will automatically increase its selling price.
Unfortunately, the additional amount a buyer is willing to pay may not justify the renovation cost.
For example, spending $30,000 on a major renovation does not guarantee a $30,000 increase in your selling price.
Buyers have different tastes, and some may prefer to renovate the property themselves.
Instead, focus on preparing the flat to appeal to potential buyers.
Simple improvements may include:
- Deep cleaning and decluttering
- Repairing obvious defects
- Repainting worn or heavily marked walls
- Improving lighting and presentation
- Arranging furniture to make spaces look more functional
The goal is to help potential buyers visualise the property as their future home without overspending on improvements that may not produce a worthwhile return.
7. How Can You Achieve a Competitive Selling Price?
Obtaining a good selling price involves more than simply advertising your property at the highest possible amount.
An effective HDB selling strategy considers four important factors.
Accurate pricing: Review actual resale transactions, competing listings and the individual attributes of your property.
Property presentation: Good photographs, clear descriptions and a well-presented home can help potential buyers assess its suitability.
Targeted marketing: Reach buyers who are genuinely interested in your flat type, estate, budget and surrounding amenities.
Negotiation and transaction planning: Consider both the offered price and the buyer's financing readiness, proposed timelines and other transaction conditions.
Overpricing a property may reduce serious enquiries, while underpricing without a clear reason may leave money on the table.
The objective should be to secure a competitive outcome that also fits your plans for your next home.
8. What Should You Do Before Putting Your HDB on the Market?
Before starting the selling process, consider the following checklist:
Confirm that you are eligible to sell your HDB flat and have fulfilled the applicable Minimum Occupation Period.
Review recent resale transactions involving comparable flats.
Check your outstanding housing loan.
Log in to your CPF Home Ownership Dashboard to review your estimated required housing refund.
Calculate your expected net cash proceeds after selling expenses.
Decide whether you intend to upgrade, downsize, relocate or purchase another property.
Understand the resale process, documentation and timelines.
Seek a professional property assessment if you would like a clearer understanding of the market.
Completing these steps will help you make a more informed selling decision.
9. Frequently Asked Questions About Selling HDB Flats in Singapore
Can I sell my HDB flat immediately after five years?
Many standard HDB flats have a five-year Minimum Occupation Period, but certain flat categories have longer requirements. You must fulfil the applicable conditions and obtain HDB's approval before selling.
Do I need to return my CPF housing grant when selling?
Generally, CPF housing grants used for your property and their accrued interest form part of the CPF housing refund required when you sell.
What if my sale proceeds are insufficient to refund my CPF?
If your property is sold at market value and the proceeds are insufficient to cover the required CPF refund after settling the outstanding housing loan, you generally do not have to top up the CPF shortfall in cash. Other obligations may still apply, and particular circumstances can affect the outcome.
Can I use my CPF refund to buy another HDB flat?
CPF savings refunded to your Ordinary Account may generally be used for another eligible housing purchase, subject to applicable CPF and housing rules.
Is it better to sell my HDB myself or engage a property agent?
Homeowners can sell their HDB flats themselves if they meet the relevant requirements and follow HDB's procedures.
However, engaging a property agent may be useful if you want assistance with pricing, property marketing, coordinating viewings, negotiations and transaction planning.
The most suitable approach depends on your experience, available time and preferred level of support.
10. Find Out How Much Your HDB Flat Could Sell For
If you're considering selling your HDB flat in 2026, knowing its potential market value is only part of the equation.
A more useful question is:
After selling my HDB flat, how much cash and CPF will I have, and what can I realistically afford next?
Understanding these figures before listing your property can help you make better decisions about selling, upgrading, downsizing or retirement planning.
Thinking of Selling Your HDB Flat? Get a personalised HDB selling assessment covering:
- An estimated market value based on comparable transactions
- An indicative selling price range
- An estimated cash proceeds calculation using your housing loan and CPF figures
- A discussion of the selling timeline and available options
- Guidance on planning your next property move
Whether you're ready to sell or just exploring your options, start by understanding what your HDB flat could be worth.
Contact us to arrange a no-obligation HDB selling consultation.
Disclaimer: Information is general and reflects rules reviewed in October 2026. Calculations are illustrative and do not constitute financial or legal advice. Selling eligibility, CPF requirements, stamp duties and other transaction conditions should be verified against the latest official guidance for your particular circumstances.